I am at work and running a macro on my system right now, so it seems like the perfect opportunity to write a blog entry. Yay!
I originally planned to write about my experiences with my Discover Card. I got the Discover Card in December for a balance transfer at 15 months no interest. I really had no intention of using the card for actual purchases, but then I started looking into their 5% cash back bonus rewards and thought I would try it out for the month of May. From April through June, the card pays 5% cash back on restaurants and movies, and for the month of May, there was an additional cash back bonus of 5% for grocery store purchases. Additionally, they have a promotion through 2012 where you get 2% cash back on telecommunications purchases (phone, internet, cable, satellite radio) that you have automatically paid with your Discover Card.
Now, I know I'm supposed to be watching our spending, but we go out to eat. We usually go out at least once on the weekend, and I go out sometimes during the week - usually on Friday's, but sometimes more often than that. It just depends on what my coworkers do for lunch. Knowing I'd be getting 5% back on each purchase that I made, and knowing that I was going to be making the purchases anyway, made me question why I wasn't taking advantage of this rewards program. I was already using my credit union card for their 1% cash back on most purchases, and it's actually worked out pretty well for me, except that I can't stop spending money.
What I decided to do in May was use my Discover Card for purchases at restaurants and grocery stores (we don't go to the movies), and my credit union card for other purchases. I was guaranteed 5% back on the Discover purchases, and 1% back on the credit union card. The 5% can be redeemed in multiple ways, and the 1% is paid out yearly into a high interest savings account (greater than 10%).
Throughout my first billing cycle (first 27 days of May), I earned more than $15 in rewards, but I'd only made about $60 in purchases at a grocery store.
Now, I should have put more thought into this, but I was trying to act quickly since the transaction had to clear by the end of the month and it was the 28th by time I saw my May statement. I went to my local grocery store with a gas station and bought their gift cards to use for gas and groceries to get the 5% cash back. If I had done more research, I would have realized that the gift cards did not earn me any fuel rewards, however if I had bought cards that earned me fuel rewards, I would not have likely paid more in activation fees than I got back, so it was a toss up. As it is, I earned $10 in cash back and will be able to pay for my gas and groceries with the gift cards. The maximum you can earn this year from the 5% cash back bonus is $315, based on current promtions, plus whatever you earn from regular purchases. My plan is to cash out the cash back rewards at the end of the year to apply towards Christmas. If I redeem my rewards for their partner gift cards, I can increase my rewards and save myself a little more.
Anyway, I planned to write more but it's time to go home. Later.
Wednesday, May 30, 2012


Wednesday, May 23, 2012
Annoyed
We're in the process of refinancing our house. I'm glad that we are, don't get me wrong, but I'm starting to see what others have complained about as far as the harp refinancing process goes.
I applied at the end of April and received the application the following week. I completed the paperwork and collected their list of documents and returned everything.
This past weekend, I received an envelope from US Bank with a new good faith estimate. It, of course, was more - to the tune of $1056 more. They said instead of a two month deposit towards escrow, I have to deposit five months worth.
Now, today, I received an email from the underwriter saying that I need to send my last two years tax returns. My problems with this are multiple.
One, why was this not included on my initial checklist of required documents? We could have returned them at the same time as everything else. Two, US Bank had us sign authorization forms for them to pull our tax transcripts. The information should be exactly the same on the transcript as on the tax return because, you know, the transcript is created based on the return. Three, they want a signed and dated copy of the return. Who do you know that files tax returns by paper? What is the purpose of a signed and dated return?
And finally, why am I jumping through so many hoops to refinance with my current lender? They know I've paid my mortgage for the past five years; every month, on time, in full. Does it matter what my tax return looks like? Has my financial position impacted my ability to pay my mortgage in this time of financial instability? As all of my neighbors have walked away from their homes, leaving mine completely worthless, have I even been late on a payment? It's not like I'm refinancing to a shorter term loan or that my payments are going up. I meet the requirements for refinancing under HARP, so what is the deal???
If I didn't think it's be a bigger hassle to find another lender, I'd scrap this refi and go elsewhere. I thought this would be the path of least resistance.
Tuesday, May 8, 2012
Another day, Another Dollar
Another day, another dollar. Things are continuing down the same path they have been. We got our refinance paperwork last week and I set to work collecting the paperwork they needed to complete our loan. Of course, last Monday my credit union sent me a message on Facebook telling me that they may be able to help me after all and that somebody would call me within a week. Yesterday was a week and I still haven't heard, so I may give another call today. If our credit union is able to do better than our current lender, then I may scrap our current loan application and eat the application and credit report cost.
I also decided to start using my Discover card for automatic payment of some of our bills. They are offering 2% cash back on automatic payments of Cable, Satellite TV, Phone, Internet, and Satellite Radio with the Discover card. I currently pay these bills manually with another rewards card and then pay them off at the end of each month so that they don't incur interest charges. My other rewards card offers 1% cash back, which is deposited into a high interest savings account, which I haven't touched in the past three years, but I thought that earning double the rewards with my Discover card would be a better financial decision. I can cash those rewards in on gift cards for places that we frequent and do more with my money, so it's a win/win for me.
It amazes me that Discover is quickly becoming my second favorite credit card (behind my credit union rewards card). Discover is the company that sued me for a defaulted credit card back in 2001 and I never thought that they would approve me for another card, as I'd always heard that they blacklist those that have previously defaulted on an account. But here I am, with a $10500 credit limit and using it effectively and to my benefit.
Anyway, it's just more of the same in our financial world. Things are slowly but surely getting better and we are making progress. That is the best we can hope for.
Monday, April 30, 2012
Refinancing
We received our application and paperwork to refinance our home this weekend. The news was even better than I had expected as they are dropping our PMI from nearly $60 per month to less than $18.
By time all is said and done, with the lower interest rate, lower PMI, and lower taxes, as well as a longer mortgage term, we will be saving about $225 a month, which will initially be applied directly to our credit cards and later will be either saved or applied towards principle. It all depends what is going on with the housing market when that time comes. If we're staying put, we'll need to pay five years off our loan. If we're leaving, we'll be saving towards a 20% downpayment to prevent PMI on the next home.
By time all is said and done, with the lower interest rate, lower PMI, and lower taxes, as well as a longer mortgage term, we will be saving about $225 a month, which will initially be applied directly to our credit cards and later will be either saved or applied towards principle. It all depends what is going on with the housing market when that time comes. If we're staying put, we'll need to pay five years off our loan. If we're leaving, we'll be saving towards a 20% downpayment to prevent PMI on the next home.
Monday, April 23, 2012
A Little Early
I may have celebrated a little too early last week. As it turns out, if you include my 401k loan, I am still over $200,000 in debt. However, I did pay off more than $700 in debt this month, and that includes what we charged for our vacation.
Yay, right!? Okay, so I know we shouldn’t have charged our vacation, but I know that my husband is getting a bonus this month and another in three months, so we’ll be able to pay it off by summer. I know we would be further ahead if we had just not taken a vacation, but we enjoyed ourselves and it was really good for us to get away as a family.
But we have gotten some good news and some “good” news in the past couple of days that may bode well for our financial future as it relates to our house. I called my current mortgage lender about refinancing and found out that I can refinance to 4.5%, as opposed to the current 6.0%. There are about $2400 in fees, including appraisal, credit report, closing costs, etc. This will lower our monthly mortgage payment about $140 a month. Because I currently have PMI on my home, they will not let me reduce my mortgage term from 30 years to 15 or 20 years. I’m not sure of the logic of this, aside from the fact that it keeps me paying PMI longer. It doesn’t matter though, because I’m going to continue paying the same amount towards my mortgage to pay my principle off quicker and ultimately get out of PMI quicker.
The other “good” news, that I put in parenthesis because it’s not really good news, but it’s better than the alternative, is that we received word on our appeal of our property value. They decreased our property value 25% for 2010, and 5% for 2011, so we should be receiving a refund of overpaid property taxes and will be paying less going forward.
The combination of these two items means we will likely see a nearly $200 decrease in our monthly mortgage payment. While we’re still stuck in a home that we hate, the extra money means that we can pay off our debt faster.
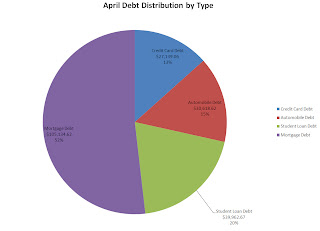
And finally, here is our current debt picture.

Yay, right!? Okay, so I know we shouldn’t have charged our vacation, but I know that my husband is getting a bonus this month and another in three months, so we’ll be able to pay it off by summer. I know we would be further ahead if we had just not taken a vacation, but we enjoyed ourselves and it was really good for us to get away as a family.
But we have gotten some good news and some “good” news in the past couple of days that may bode well for our financial future as it relates to our house. I called my current mortgage lender about refinancing and found out that I can refinance to 4.5%, as opposed to the current 6.0%. There are about $2400 in fees, including appraisal, credit report, closing costs, etc. This will lower our monthly mortgage payment about $140 a month. Because I currently have PMI on my home, they will not let me reduce my mortgage term from 30 years to 15 or 20 years. I’m not sure of the logic of this, aside from the fact that it keeps me paying PMI longer. It doesn’t matter though, because I’m going to continue paying the same amount towards my mortgage to pay my principle off quicker and ultimately get out of PMI quicker.
The other “good” news, that I put in parenthesis because it’s not really good news, but it’s better than the alternative, is that we received word on our appeal of our property value. They decreased our property value 25% for 2010, and 5% for 2011, so we should be receiving a refund of overpaid property taxes and will be paying less going forward.
The combination of these two items means we will likely see a nearly $200 decrease in our monthly mortgage payment. While we’re still stuck in a home that we hate, the extra money means that we can pay off our debt faster.
And finally, here is our current debt picture.


Wednesday, April 18, 2012
Milestone!
I input all of the payments we've made this month, as I do after every pay day. I put all of our new balances in, taking into account what we spent on vacation. The only outstanding payment we have for April is my car, but I can estimate the balance based on interest rates and fixed payment amounts.
And then I came to a shocking and exciting realization.
For the first time since I started my debt payoff journey, we owe less than $200,000 in debt!
This months debt total is $199,564.32!
Slow and steady wins the race, right?
In other news, I'm trying to refinance our house. Supposedly, HARP 2.0 eliminated a cap on LTV and appraisals on your home. As I am learning, this is not necessarily so. Since financial institutions have a choice in whether they want to offer HARP refinancing or not, most of them are not willing to provide refinancing through this program. Why should they, I guess, when they're making a profit off of those of us that are locked into high interest rates and haven't walked away from our homes yet.
I tried to refinance through my credit union yesterday, but they enforce a 125% LTV cap on their HARP loans. We're looking at closer to 148% based on Zillow's values. Even if we used the higher assessment we received from the auditors office for tax purposes, we're still at 133% LTV.
I hate that we live in a society where I'm being punished for being responsible and paying my mortgage, unlike the majority of my neighbors. I don't know if our situation would be more bearable if we were paying less on our home, but it would certainly lessen the sting. Every day I ask myself why we're still paying our mortgage when all of our neighbors have walked away and the current owners paid 1/3 of what we did for our home. We're gluttons for punishment, I guess.
We have to make a pretty big repair to our home, to the tune of over $8000, but I don't know where we're going to find the money. In better times, we might have been able to take out a home equity line of credit, but since our equity is negative, there is nothing to take out. It's our sewer line, and it's a ticking time bomb. The walls are cracked and it has started to shift in about 1/4-1/2 of an inch. I know we need to fix it, but I don't know where we'll find the money.
Roto Rooter was pretty shady about the whole thing; they told us in our home that it would be a max $4000 to have the work done, so I took a $4000 loan out of my 401k, only for them to give us a proposal of $8175. When I told him he had quoted us $4000 at our home, he said there was no way he would have quoted that because it was impossible and told me to take out a loan for the other $4000. I told him I took out a loan for the first $4000 and it wasn't even in the ballpark of what we were willing to do for our home at this time.
I applied for a new job too. I'm not sure if I am ready to leave where I am, but the job I applied for pays significantly more, and it's more in line with the career path I'm following. We'll see if I even get an interview, and then I will start making decisions if it's necessary.
Alas, I must get back to work, but I wanted to share my good news.
Saturday, March 3, 2012
Miscalculated
I'm glad I slept on it last night and reran the numbers. It made me realize that I miscalculated; the loan payments were biweekly, not monthly, so we can't afford it, and the savings wouldn't be that substantial anyway. I'm back to the drawing board.
My husband and I had a huge argument about budgeting and finances this evening. It ended with me telling him that I just wanted us to be on the same page when it comes to money, because no matter how much I try to pay off debt, it's not going to happen unless we both are willing to change our spending habits. That has led to me deciding tonight that I need to write out my plan to get us out of debt and to lay it out to him so he knows EXACTLY what my plans are and we can BOTH stick to these plans, instead of spending impulsively.
That said, I need to figure out exactly what my plan is.
Subscribe to:
Posts (Atom)